Institutional FX Insights: Credit Agricole FX Weekly 9/10/26
1. French Fiscal Risks & EUR Dynamics
Budget Debate & Ratings Horizon: The French National Assembly formally reviews the 2027 draft budget next Tuesday, setting up intense parliamentary scrutiny as the government seeks to enforce fiscal consolidation. Moody’s rating review on October 23 represents a crucial market test for sovereign credit spreads.
Contagion & Sovereign Spreads: Financial markets remain focused on whether French sovereign debt (OAT) widening spreads overflow into broader European Government Bond (EGB) markets (e.g., Italian BTPs or Spanish BONOS). A systemic widening could tighten overall Eurozone financial conditions, complicating ECB policy.
ECB Tightening Support: Despite headwind drivers (energy costs, looming EU-China trade frictions), market expectations of sustained ECB policy rates continue to bolster short-term EUR rate differentials.
2. Election Cycles & FX Hedging Strategy
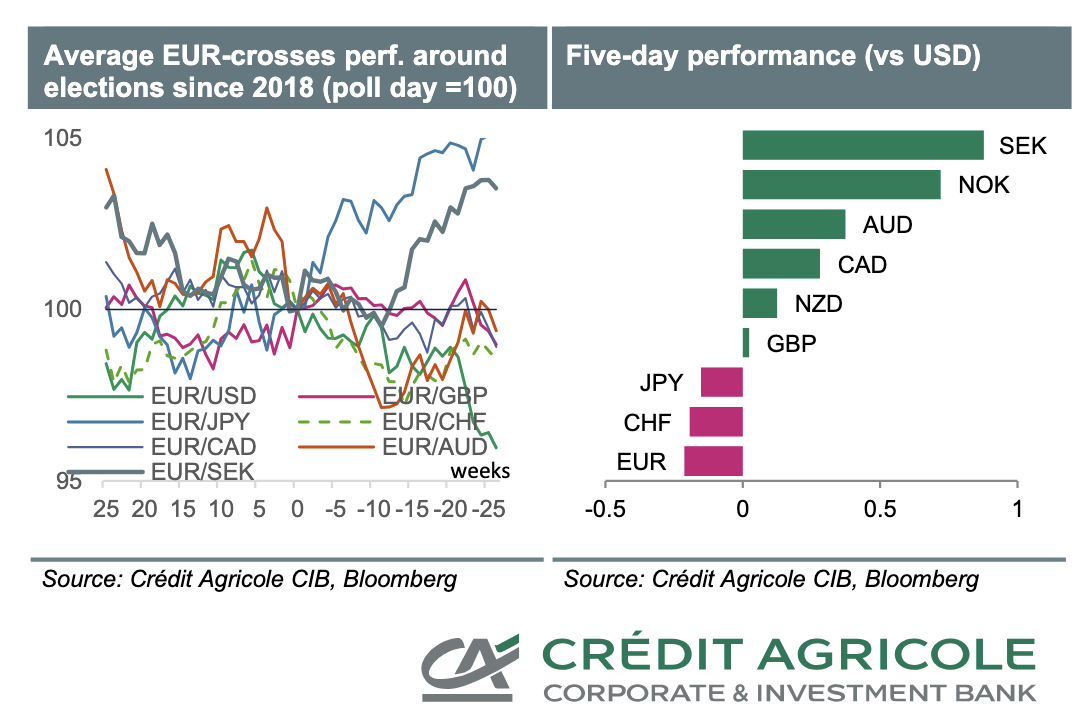
Historical Performance Pattern: Historical performance around French and Italian national elections (since 2018) shows a distinct pre- vs. post-election trend:
Pre-Election: EUR typically appreciates against major G10 currencies.
Post-Election: EUR frequently experiences a sell-off, particularly against USD, CHF, and AUD.
Divergent Pairs: Opposite trends occur against JPY, GBP, SEK, and NOK, making these specific crosses effective EUR-downside hedges ahead of upcoming votes.
Scenario Projections: Analysis across post-election political outcomes targets a wide 1.05–1.19 range for EUR/USD, with a baseline projection near 1.17 by Q4 2027.
3. G10 Currency Drivers
US Dollar (USD): Reaping safe-haven inflows driven by European fiscal uncertainty. Near-term market attention shifts to incoming U.S. CPI inflation, retail sales data, and public commentary from Federal Reserve leadership, including Chair Kevin Warsh. Higher data surprises or hawkish signals remain necessary for substantial further upside given existing market pricing.
British Pound (GBP): While outperforming the Euro, GBP resilience remains constrained by softening UK macroeconomic growth prospects ahead of upcoming GDP data releases and Bank of England MPC communications.
Australian Dollar (AUD): Sensitive to domestic employment indicators for September alongside broader shifts in global risk sentiment.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!